Financial Due Diligence: Everything You Need to Know
 By
Reviewed by Devendra Kumar Malhotra, Registered Valuer (Plant and Machinery), IBBI/RV/05/2018/10424 | Sapient Services Pvt. Ltd., New Delhi | Last updated: October 2026
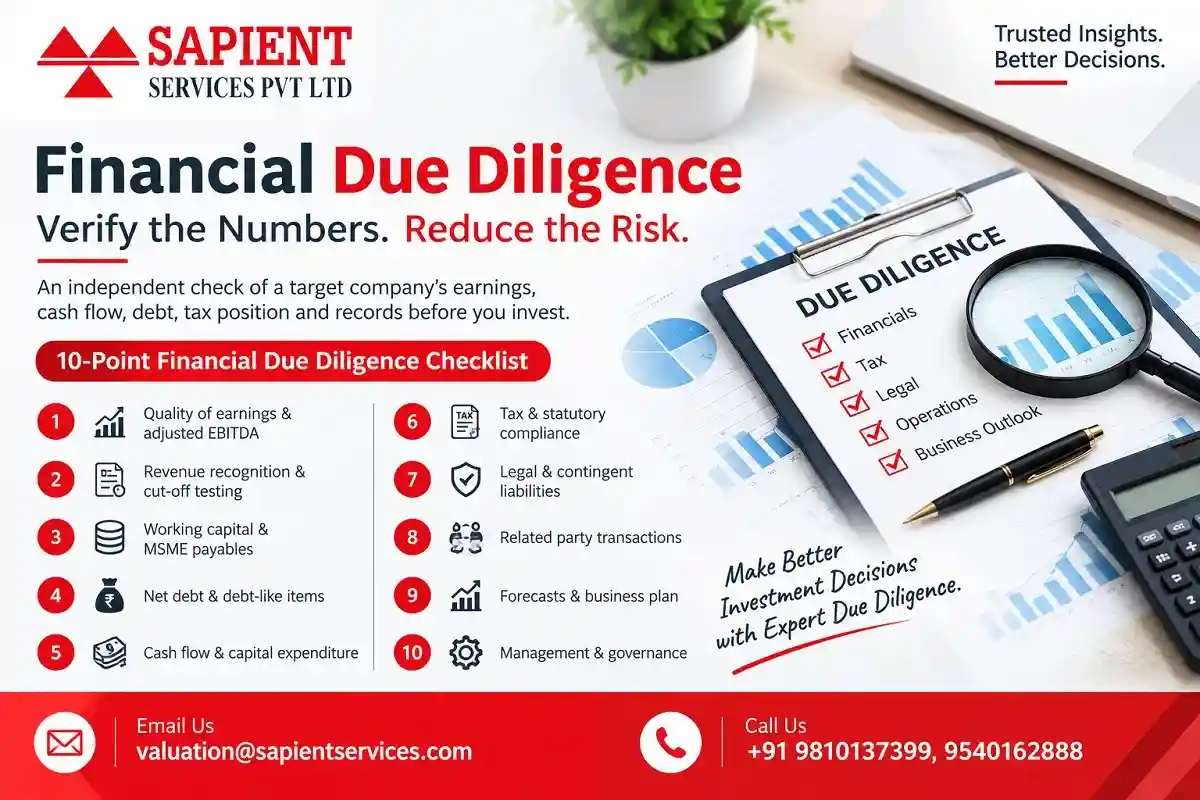
Quick answer: Financial due diligence is an independent check of a target company’s earnings, cash flow, debt, tax position and records before you invest. The ten-point checklist below runs from earnings quality to the forecast.
A pitch deck presents the business as management sees it. Financial due diligence tests that picture against invoices, bank statements and tax filings before you commit money.
Two recent changes bear on the checks. The Labour Codes, in force since 21 November 2025, changed the wage definition used for gratuity. And the Income-tax Act, 2025 replaced the 1961 Act from 1 April 2026, though the old Act still governs earlier tax years.
Work through the checklist before you sign. For an independent team, call +91 9540162888.
What financial due diligence covers
Financial due diligence is a buyer-side review of a target’s historical results, cash flow, debt, tax exposure and forecast. Its job is to say whether the numbers are reliable enough to set a price.
It is not a statutory audit, where an auditor gives an opinion on whether past accounts show a true and fair view under the Companies Act, 2013.
A due diligence team usually delivers a findings report instead. It sits alongside legal and commercial reviews, which our guide to due diligence in India explains, and it depends on the documents supplied and the agreed scope.
A 10-point financial due diligence checklist
If time is short, start with checks 1, 4 and 5. Earnings, net debt and cash flow feed straight into the price.
1. Quality of earnings and adjusted EBITDA
Many deals use an EBITDA-based multiple as one input to price, so adjusted EBITDA deserves the closest look. Ask management for a bridge from reported profit to adjusted EBITDA, with a document behind each adjustment. Every rupee of add-back is then multiplied.
Red flag: an “exceptional” cost that appears every year. A recurring one-off is an ordinary expense.
2. Revenue recognition and cut-off testing
Under Ind AS 115, a sale counts when the customer gets control of the goods or services, not when the invoice is raised. Check invoices dated in the last week of the year.
Reconcile revenue in the books to GST returns, bank credits and the income-tax filing. Read post-year-end credit notes too, since they can reverse sales booked early.
Red flag: a gap between booked revenue and GST turnover that management cannot explain line by line.
3. Working capital and MSME payables
Working capital sets the closing adjustment. The target level, the peg, should reflect a normal month, so analyse monthly balances over enough history to show seasonality, often twelve months or more. Test each part:
- Debtors: ageing, and collections after year end.
- Inventory: slow-moving and obsolete stock against the provision.
- Creditors: payables stretched just before the deal date.
Section 15 of the MSMED Act, 2006 requires payment to micro and small suppliers by the agreed date, capped at 45 days from acceptance, or within 15 days where there is no written agreement.
For tax years beginning before 1 April 2026, a late payment defers the company’s deduction until the cash leaves (Section 43B(h) of the 1961 Act). Section 37(2)(g) of the Income-tax Act, 2025 carries the rule forward.
Red flag: creditors that jump shortly before closing. They flatter cash, and the buyer pays them after completion.
4. Net debt and debt-like items
A simplified transaction bridge starts with enterprise value and adjusts for net debt and the other items the parties agree to treat as debt, cash or working capital. Hidden debt cuts the price directly.
Compare the balance sheet with lender sanction letters and with the charges registered against the company on MCA records. Then look for items that behave like debt:
- Lease liabilities under Ind AS 116, where it applies; whether they count as debt varies by deal.
- Deferred consideration for earlier acquisitions.
- Unpaid tax, provident fund and other statutory dues.
- Gratuity and leave encashment provisions.
- Guarantees for group companies, and contingent liabilities under Ind AS 37. Ask for the legal status of each.
Red flag: a lender list that does not match MCA charge records. Reconcile both with the debt schedule before agreeing equity value.
5. Cash flow and capital expenditure
Cash is harder to arrange than profit. Compare operating cash flow with EBITDA for three years, and ask for an explanation of any persistent gap.
Split capital expenditure into maintenance and growth; a company that cut maintenance to lift profit leaves the repair bill to the next owner. Match the fixed asset register to the plant on site too, since an asset that exists only in the register inflates the balance sheet.
Red flag: three years of rising profit with operating cash flow well below EBITDA.
6. Tax and statutory compliance
In a share acquisition, historical tax exposures generally remain with the target, so the buyer must price them or cover them through warranties and indemnities. Ask for assessment orders, pending demands and appeal status for every open year, noting which Act governs each.
On GST, reconcile input tax credit with GSTR-2B. Demands for FY 2024-25 onwards fall under Section 74A of the CGST Act, with notices allowed up to 42 months after the due date of the annual return. Earlier years fall under Sections 73 and 74.
On labour dues, test gratuity and leave provisions against the wage definition and rules that apply to the establishment and period, and ask whether they were re-measured under Ind AS 19 or AS 15.
Where an Indian company has issued equity instruments to a person resident outside India, check the FC-GPR filing for each allotment. It is due within 30 days, and late filings attract the RBI’s Late Submission Fee.
Red flag: an open demand or an unfiled return that the management accounts never mention.
7. Related-party transactions
Related-party dealings are the easiest place to shape a company’s numbers. Ask for a list of every entity the promoters and their families own or control, then search the ledgers for each name. Look for rent, loans, purchases and sales on terms an outsider would not get.
Section 188 of the Companies Act, 2013 requires board approval, plus shareholder approval above the limits in the rules, for specified related-party contracts outside the ordinary course of business or not at arm’s length. Check the minutes and the Ind AS 24 disclosures.
Red flag: a balance owed by a promoter entity that grows every year. It is a loan in all but name.
8. Customer and supplier concentration
Ask for revenue by customer for three years, then ask what happens if the largest one leaves. Read its contract for termination and change-of-control clauses before you sign.
Test suppliers the same way, and compare credit terms on both sides.
Red flag: a key contract that the customer can end at short notice once ownership changes.
9. Books, controls and the audit report
Read the auditor’s report in full for qualified opinions, emphasis-of-matter paragraphs and, where CARO 2020 applies, remarks on loan defaults and unpaid statutory dues.
For applicable companies, Rule 11(g) of the Companies (Audit and Auditors) Rules, 2014 requires the auditor to report whether the accounting software had an audit-trail feature that operated throughout the year for all transactions, was not tampered with, and was preserved as required.
If an auditor resigned before the term ended, read the Form ADT-3 filing, where applicable, and the reason given.
Red flag: an adverse or qualified observation on the audit trail. It means changes to the books may not be traceable.
10. Forecast and projections
A discounted cash flow valuation is only as good as the forecast behind it. Compare the last three budgets with actual results. If management missed each one by a wide margin, trust the new plan less.
Test the assumptions one at a time: volume against installed capacity, price against signed contracts, and margin against recent input costs. Then build the downside case yourself.
Red flag: a steep jump in year two with no capital expenditure to support it.
What to do with a financial due diligence finding
Every finding should end in a decision: change the price, change the terms or step back. A rough guide:
- Recurring “one-off” costs: lower the maintainable EBITDA and reopen the price.
- Obsolete stock or stretched creditors: reset the working-capital peg.
- Undisclosed debt: reduce equity value or require repayment at closing.
- Tax or statutory exposure: seek an indemnity, an escrow or a price cut.
- Dependence on one customer: test the forecast without that customer.
To have an independent team test a target’s numbers, email valuation@sapientservices.com.
Documents to request for financial due diligence
Ask the target for four things first:
- The bridge from reported profit to adjusted EBITDA, with support.
- Monthly revenue by customer for three years, with GST returns for the same period.
- Lender statements and a list of every loan, guarantee and lease.
- Three years of auditor’s reports, with the related-party and contingent liability notes.
Read the four against each other. Where they disagree is where to dig.
Frequently Asked Questions
Q: How long does financial due diligence take?
A: There is no fixed period. It depends on the size of the target, the number of entities and how quickly management supplies documents.
Q: Is financial due diligence needed for a small investment?
A: Scale the work to the cheque. A focused review of earnings quality, net debt and tax dues can cover the main risks of a small minority stake; a control deal needs the full checklist.
Q: Who should carry out financial due diligence in India?
A: Buyers commonly use chartered accountants with transaction experience, so check track record and independence. Add a Registered Valuer when the deal also needs a share or asset valuation.
Q: How is financial due diligence different from a valuation?
A: A valuation estimates what the business is worth. Financial due diligence tests whether the numbers feeding that valuation are reliable.
Get an independent review
Sapient Services Pvt. Ltd. is a valuation and advisory firm headquartered in Okhla Phase II, New Delhi (Delhi NCR), with IBBI-registered valuers on its team. To discuss a transaction, call +91 9540162888 or email valuation@sapientservices.com. You can also read about our due diligence services in India.
Sources: Income Tax Department transition FAQs (Income-tax Act, 2025, Section 536); MSMED Act, 2006, Section 15; CGST Act, 2017, Section 74A; Companies Act, 2013, Section 188; Companies (Audit and Auditors) Rules, 2014, Rule 11(g); RBI FEMA reporting; Ministry of Labour and Employment.
This article is general information, not legal, tax or investment advice. Provisions are stated as of October 2026. Confirm how they apply to your transaction with a qualified professional.